What Canton Homeowners Should Know Before Reviewing a Policy
Buying a home in Canton is only part of the financial picture. Protecting it with the right home insurance matters just as much, especially in an area where fast-growing neighborhoods, changing property values, and severe weather can all affect what a policy should look like. Many homeowners assume their current policy automatically keeps pace with inflation, renovations, or new risks, but that is not always true. This guide breaks down the most important home insurance tips for homeowners in Canton, GA so readers can spot coverage gaps, ask better questions, and make more informed decisions before storm season, a water loss, or a costly claim puts the policy to the test.
Why Home Insurance Deserves a Fresh Look in North Metro Atlanta
Canton sits in a part of metro Atlanta where growth has been steady, home prices have changed quickly, and rebuilding costs can rise faster than many people expect. That combination makes old assumptions risky. A policy written a few years ago may not reflect today’s labor costs, material prices, or the value of upgrades like a finished basement, new roof, or expanded outdoor living space. Local weather patterns also matter. Wind-driven rain, hail, falling trees, and sudden plumbing leaks are common claim drivers across Cherokee County and nearby communities such as Woodstock, Holly Springs, and Ball Ground. Reviewing coverage regularly helps homeowners keep protection aligned with real-world conditions instead of outdated estimates.
Check Whether Your Dwelling Limit Matches Rebuilding Reality
One of the most important tips for Canton homeowners is to focus on rebuilding cost, not market value. The price someone paid for a house includes land, neighborhood demand, and school district appeal, but insurance for the dwelling is meant to cover the cost of repairing or rebuilding the structure itself. In neighborhoods around Canton and toward Woodstock or Waleska, replacement costs can vary based on square footage, roof type, custom finishes, and contractor availability after a major storm. If the dwelling limit is too low, a homeowner could face a large out-of-pocket balance after a serious fire or wind loss. Reviewing the home’s features, age, upgrades, and local construction costs can help keep that limit realistic.
Understand What the Policy Covers and What It Leaves Out
Homeowners often discover too late that a standard policy has exclusions and limits that matter a lot during a claim. In plain terms, a typical home insurance policy may help cover the house, detached structures, personal belongings, liability, and temporary living expenses after a covered loss. But that does not mean every type of damage is included. Flooding from rising water is generally excluded, and issues caused by wear and tear, neglect, or long-term maintenance problems are usually not covered either. For Canton homes near creeks, sloped lots, or areas with drainage concerns, that distinction can be especially important. It also helps to review sub-limits for jewelry, firearms, electronics, and water backup so there are fewer surprises later.
Choose a Deductible That Fits Both Budget and Risk Tolerance
A higher deductible can lower monthly or annual premium costs, but it should never be set at a level that would create financial strain after a loss. Homeowners in Canton should think through realistic claim scenarios. If a summer storm damages shingles, a tree limb breaks a section of fencing, or a plumbing leak affects flooring and drywall, how much could be paid out of pocket without disrupting other finances? That is the practical question. Some policies also use separate wind or hail deductibles, which can change claim math significantly. The best deductible is not automatically the lowest or highest option. It is the amount that balances affordability today with the ability to respond calmly and quickly when repairs are suddenly needed.
Document Upgrades, Personal Property, and Safety Features
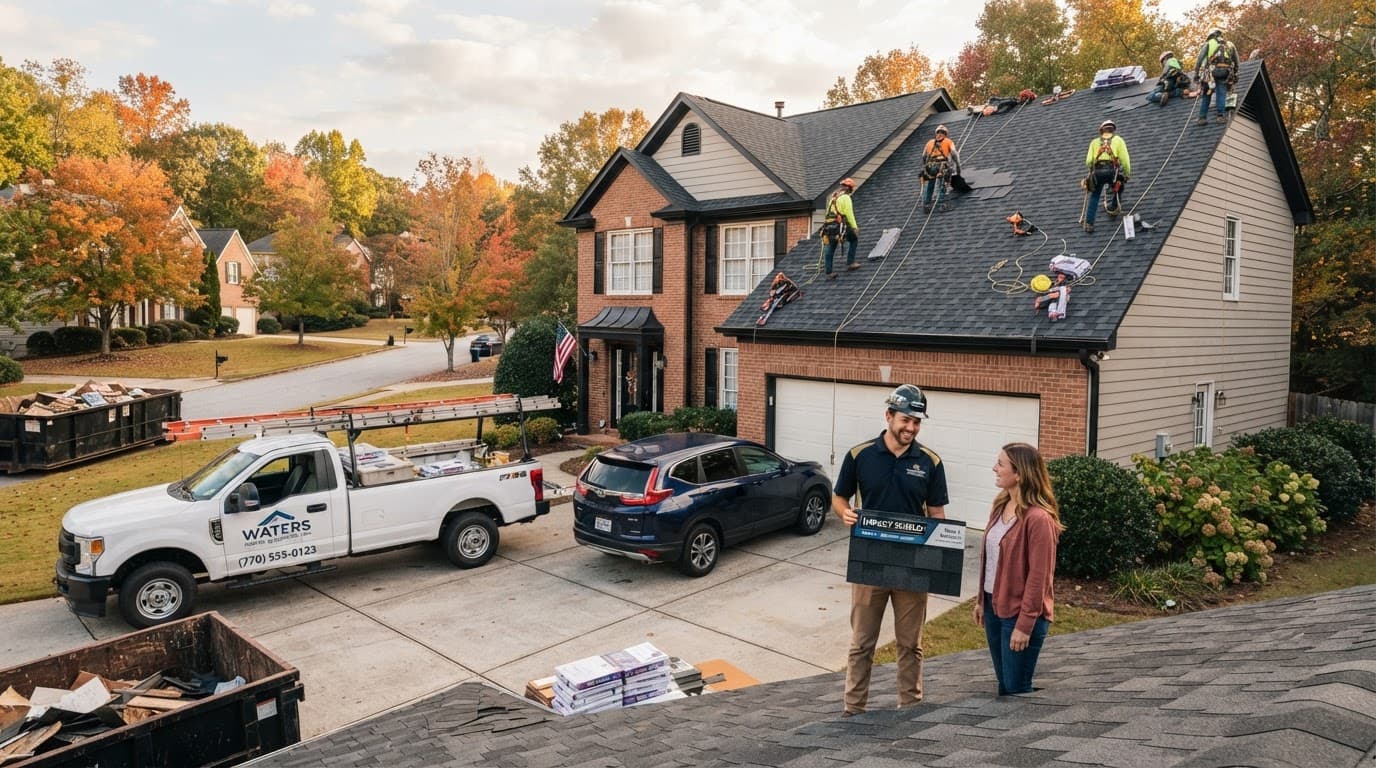
Many Canton homeowners improve their homes over time but forget to update their insurance information. A renovated kitchen, upgraded flooring, detached garage, finished bonus room, or new deck can all affect coverage needs. The same goes for personal property. If a household has added expensive tools, furniture, appliances, collectibles, or home office equipment, older policy records may no longer tell the full story. A simple home inventory can make a big difference. Taking photos, saving receipts when possible, and noting serial numbers for major items can streamline a future claim. Safety improvements deserve attention too. Alarm systems, leak detectors, updated electrical work, and impact-resistant roofing may influence underwriting or discounts while also reducing the chance of a major loss.
Think About Water Risk Beyond Just Heavy Rain
Water damage is one of the most misunderstood parts of home insurance, and it is a major issue for many homes in and around Canton. Sudden and accidental discharge from a burst pipe may be covered, while seepage over time or flood-related water entering from outside usually is not. That makes it important to know the source of the water in each scenario. Homes with basements, lower-level finished spaces, older plumbing, or nearby drainage channels may want to pay close attention to options such as water backup coverage. Even in communities like Kennesaw, Marietta, Roswell, and Alpharetta, where housing styles vary, the same rule applies: small water problems become expensive fast. Prevention, maintenance, and policy clarity work best together.
Local Factors That Matter in Canton and Nearby Communities
Canton homeowners face a mix of local conditions that should shape insurance decisions. North Georgia weather can bring strong thunderstorms, hail, lightning, and fallen trees, especially in warmer months. Older homes may have aging roofs, plumbing, or electrical systems that deserve close review, while newer subdivisions may have higher replacement costs due to current labor and material pricing. Proximity to Woodstock, Holly Springs, Acworth, and Cumming can also influence shopping behavior because homeowners often compare homes, contractors, and premiums across nearby markets. In Cherokee County, sloped lots, wooded properties, and finished basements are common features that can affect claims severity. Local relevance is not just about ZIP code pricing. It is about how homes are built, maintained, and exposed to risk in everyday life.
Key Takeaways for Smarter Home Insurance Decisions
Key Points
- Review dwelling coverage based on rebuild cost rather than sale price or loan amount.
- Check exclusions carefully, especially for flood, maintenance issues, and certain water losses.
- Choose a deductible that would still be manageable after a roof, plumbing, or storm-related claim.
- Update the policy after renovations, additions, or major purchases so coverage keeps up with the home.
- Create a home inventory with photos and receipts to make claims easier and more accurate.
- Ask about water backup, liability limits, and personal property sub-limits if the home has higher-risk features.
- Revisit the policy regularly because construction costs and property values around Canton can change quickly.

How to Take the Next Step With Confidence
The most useful next step is to compare your current policy against your home as it exists today, not as it looked when coverage first started. That means confirming square footage, upgrades, detached structures, roof age, valuables, and deductible choices. It also means asking direct questions about exclusions, claims handling, and optional endorsements that may fit a Canton property better. Homeowners in Canton, Woodstock, Smyrna, Ball Ground, and surrounding parts of North Metro Atlanta can benefit from gathering a few quotes side by side and reviewing them line by line instead of focusing only on price. A lower premium is helpful only if the coverage still performs when it matters. A careful review now can prevent expensive surprises later.