Older Homes Can Need a Different Insurance Approach
Older homes in Roswell attract buyers for good reason. They often offer mature trees, established neighborhoods, unique architecture, and details that newer construction rarely matches. The tradeoff is that insurance for an older house is rarely as simple as insuring a newer build. Age alone does not make a home harder to cover, but older materials, outdated systems, and higher rebuilding costs can change what kind of policy makes sense. For homeowners comparing options in Roswell, Woodstock, and nearby North Metro Atlanta communities, the key is understanding that a standard policy may need adjustments to truly match the property.
Why This Matters More in the Roswell Area
Roswell has many homes built decades ago, including properties in established neighborhoods where renovation quality can vary widely from one house to the next. In this part of Georgia, older homes may face a mix of weather exposure, tree-related claims, water damage risks, and wear on major systems such as roofs, plumbing lines, and electrical panels. A house that looks beautifully updated on the surface may still have hidden components that raise claim costs. That is why insurance carriers often look closely at the age of the roof, the type of wiring, the plumbing materials, and whether key updates were completed with permits. These details can affect eligibility, premiums, and what losses are actually covered.
Replacement Cost Can Be the Biggest Surprise
One of the biggest mistakes owners of older homes make is assuming market value and rebuild cost are basically the same. They are not. In Roswell, a home may have architectural details, plaster walls, custom millwork, original hardwoods, or nonstandard room layouts that cost more to rebuild than a typical modern house. If a covered fire or major storm loss happens, replacement cost coverage becomes a central issue. Homeowners should review whether their dwelling limit reflects current labor and material costs in the area, not just what the house sold for. Extended replacement cost or ordinance and law coverage can also matter because older homes may need substantial upgrades to meet current building codes during repairs.
Aging Electrical, Plumbing, and Roof Systems Change Risk
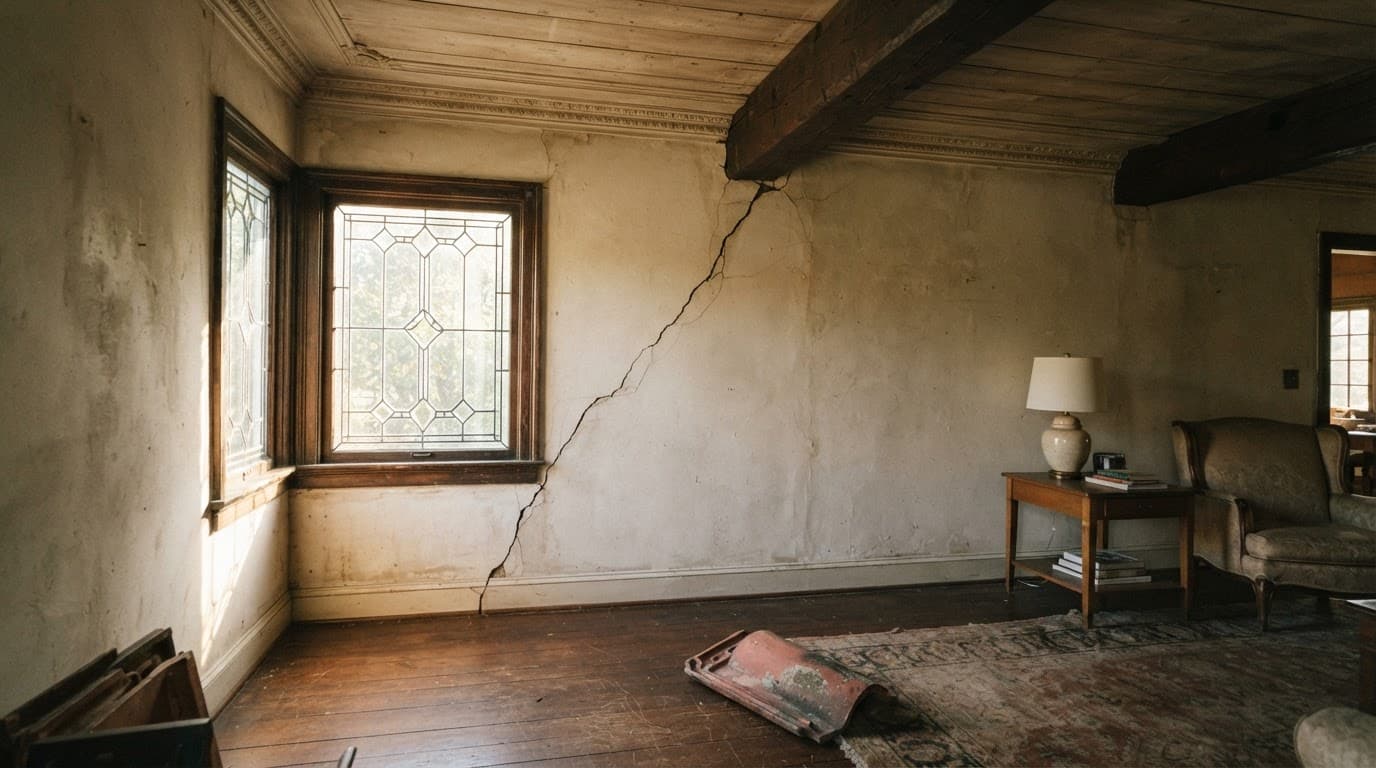
Insurance companies pay close attention to the systems behind the walls because many expensive claims begin there. Older electrical wiring can increase fire risk, especially if the panel is outdated or past modifications were done inconsistently. Plumbing is another common issue. Older supply lines or drain systems can be more prone to leaks, corrosion, and sudden failures that damage floors, cabinets, and drywall. Roof age matters just as much, particularly in Georgia where wind, heavy rain, and falling limbs can turn a minor weakness into a major claim. In some cases, an older home may still be insurable, but only after updates are made or after the homeowner accepts specific limitations tied to those systems.
Policy Exclusions and Endorsements Deserve Extra Attention
Owners of older houses should read beyond the declarations page and focus on how the policy handles settlement, exclusions, and endorsements. Some policies may settle roof losses on an actual cash value basis rather than full replacement cost, which can leave a much larger out-of-pocket expense after depreciation. Water backup, service line damage, equipment breakdown, and hidden water seepage are other areas worth reviewing carefully. In Roswell and nearby places such as Alpharetta and Marietta, mature landscaping and finished basements can also increase claim complexity. A homeowner may need optional coverage to close gaps that are easy to overlook during a quick quote comparison. The best policy for an older home is often the one that matches the house’s real condition, not just the cheapest premium.
Renovations Can Help, but Documentation Matters
A renovated older home can sometimes qualify for better pricing or broader coverage, but insurers usually want proof of what was actually updated. If the roof, HVAC, plumbing, wiring, windows, or foundation work was replaced, homeowners should keep invoices, inspection reports, and permit records organized. That documentation can help during underwriting and can also make claim handling smoother later. This is especially important when a home in Roswell has been partially renovated over time rather than fully modernized at once. A kitchen remodel may look impressive, but it does not reduce risk the same way a full electrical rewire does. When comparing policies, homeowners should be prepared to explain the age of each major component, not just the age of the house itself.
Local Conditions Around Roswell Add Another Layer
Roswell’s mix of older neighborhoods, tree canopy, sloped lots, creeks, and changing weather patterns creates a very specific insurance environment. Homes near wooded areas can see more roof and siding claims from branches and wind-blown debris. Heavy rain can expose drainage issues around older foundations or basements, while aging exterior materials may be less resilient during severe weather. These concerns are also familiar in nearby communities like Woodstock, Canton, and Kennesaw, but Roswell stands out because many homes combine age, high property values, and custom features. That combination makes accurate coverage even more important. A policy should account for local rebuild costs, the home’s physical condition, and the possibility that repairs on an older structure take longer and cost more.
Key Takeaways for Owners of Older Homes
What to Review Before Choosing Coverage
- Check dwelling limits against current rebuilding costs, not sale price or tax value.
- Ask how roof claims are settled and whether depreciation could reduce a payout.
- Review the age and type of wiring, plumbing, HVAC, and roofing before requesting quotes.
- Consider ordinance and law coverage if repairs might trigger code upgrades.
- Keep records of renovations, permits, and contractor invoices for underwriting support.
- Look at optional protections such as water backup, service line, and equipment breakdown coverage.
- Compare exclusions carefully because two policies with similar premiums may protect very different risks.

Next Steps Before You Buy or Renew
If you own an older home in Roswell or are thinking about buying one, the smart next step is to review the property the way an underwriter would. Gather details on the roof age, electrical system, plumbing materials, past claims, and any major updates. Then compare quotes based on the same coverage limits and endorsements so the differences are meaningful. For readers in Roswell, Woodstock, Acworth, Cumming, and surrounding areas, this process can help avoid the common problem of being underinsured or surprised by exclusions after a loss. Older homes can absolutely be insured well, but they usually need a more tailored policy review than a newer house.